Djerriwarrh maintains enhanced dividend yield
Quick read
Net Operating Result of $19.7 million 1HFY26, down 6.0% on the from the corresponding period
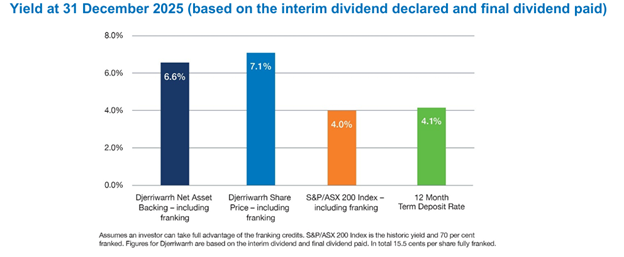
Interim fully franked dividend of 7.25 cents per share maintained; grossed-up yield of 6.6% on NTA (+2.6 ppts above index)
Six-month portfolio return of 2.1% including franking, compared with the S&P/ASX 200 Accumulation Index return of 4.2% including franking
Net tangible asset backing of $3.35 per share (pre-tax) on 31 December 2025
Quarterly dividend payments to commence in May 2026
For the half-year ended 31 December 2025, Djerriwarrh Investments (DJW) continued to deliver an enhanced dividend yield supported by its disciplined option-writing strategy and strong operating income.
While portfolio returns were modest relative to the broader market - reflecting sector composition and the Company’s income focused mandate - Djerriwarrh maintained its fully franked interim dividend and reaffirmed a transition to quarterly dividend payments from May 2026.
Sustaining yield amid sector rotation and market volatility
Djerriwarrh’s net operating result was $19.7 million, 6.0% lower than the prior corresponding period, but sufficient to fully fund the interim dividend without reliance on realised capital gains. Operating income of $16.6 million reflected reduced contributions from several holdings, including the absence of last year’s Woolworths special dividend and the impact of bank option exercises, which trimmed positions at elevated valuations.
The portfolio delivered a total return of 2.1% including franking for the six months to 31 December 2025, compared with the S&P/ASX 200 Accumulation Index return of 4.2%. Returns over the 12-month period were 5.5% versus the Index’s 11.5%. Relative performance was influenced by the strong rally in gold and critical minerals—sectors where Djerriwarrh historically has limited exposure due to their cyclicality, lower dividend contribution and more constrained option-writing opportunities.
Several core holdings also weighed on performance, including EQT Holdings and CSL, while positive contributors included BHP, Rio Tinto, ANZ, Newmont, Transurban, Ampol and Westpac.
"Our relative underperformance this half was heavily impacted by the cumulative effect of being underweight in gold and critical minerals companies, which have risen significantly. Djerriwarrh typically avoids exposure to small and mid-cap companies in these sectors as they are highly cyclical and do not produce dividends of any significance, making it difficult to write call options over them, commented Brett McNeil, Djerriwarrh Portfolio Manager.
Enhanced dividends delivered with quarterly payments commencing in May
The Board declared an interim fully franked dividend of 7.25 cents per share, unchanged from last year. Based on NTA as of 31 December 2025, the grossed-up dividend yield was 6.6%, representing an enhanced yield of 2.6 percentage points above the broader market when including franking.
Djerriwarrh also confirmed that quarterly dividend payments will commence in May 2026, replacing the previous half-yearly schedule.
Tactical option management and capital redeployment
Djerriwarrh maintained a disciplined approach to option coverage throughout the period, balancing income generation with the need to participate in rising markets. Option income totalled $7.5 million for the half, with premiums predominantly generated from BHP, Woolworths, CSL, Macquarie, Transurban, ARB and Goodman Group.
Option coverage began FY2026 at 32%, dipped to 28% following July exercises, and was subsequently increased to between 40% and 45% during the market rally into December. The half-closed with 37% call coverage, providing a solid base of option income already written for the second half.
Portfolio adjustments reflected a measured approach to valuation and dividend sustainability. Gains were crystallised through option exercises in ANZ, Rio Tinto, Telstra, NAB, Westpac and Region. Capital was redeployed into Telstra, Woolworths, Region and Transurban.
New positions were established in Sigma Healthcare, leveraging its scaled post-merger Chemist Warehouse platform. Holdings in PEXA and Domino’s Pizza Enterprises were fully exited.
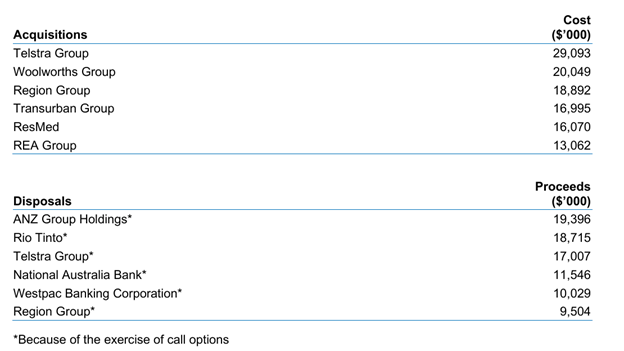
"In a highly valued market, we allowed many option positions to be exercised—particularly in the major banks, where valuations remain historically high. We chose not to buy these back, instead redeploying capital into high-quality companies trading at more attractive prices, such as Telstra and Sigma Healthcare. We enter the second half with a solid base of option income already written. This disciplined approach ensures we can balance immediate income generation with long-term capital growth”, said McNeil.
Outlook
Equity valuations remain broadly elevated relative to long term averages for price to earnings and dividend yield . Against this backdrop, Djerriwarrh remains defensively positioned while selectively adding to high-quality businesses where valuation and income potential are aligned.
Market-wide dividends are expected to be flat to slightly lower in FY2026; however, Djerriwarrh’s income base is now more diversified, with less reliance on the major banks and a more balanced contribution from miners, supermarkets and telecommunications businesses.
With no open put options and call coverage of 37% entering 2026, the options book is well placed to support income through the year, with some written positions currently in the money potentially leading to further portfolio adjustment if markets remain firm.